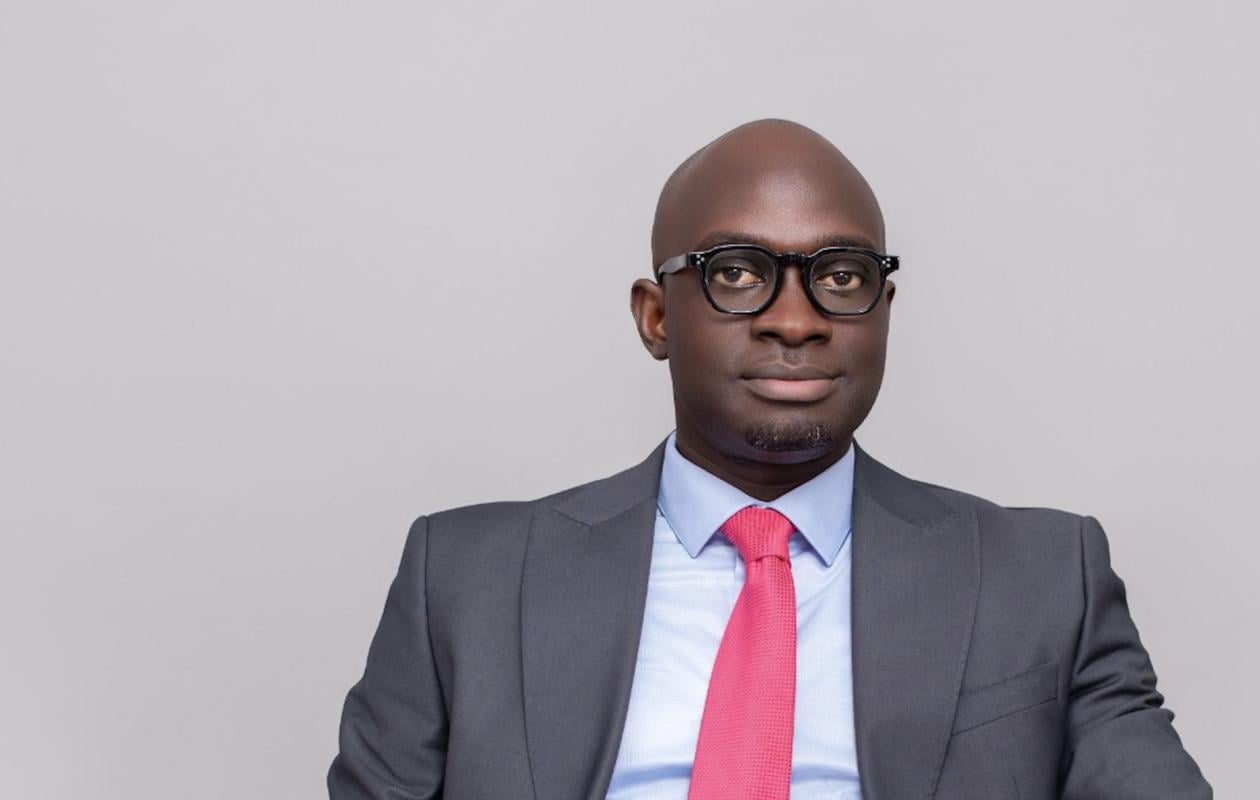
Un chemin possible pour le traitement de la dette du Sénégal (Par Seydina Alioune NDIAYE, Économiste - Associé Senquant)
Abstract. With a view to Senegal's return to the international stage and as a prelude to the inevitable debt restructuring, this contribution outlines a three-dimensional approach for successful debt restructuring. The challenge lies in clear-sightedness and foresight, to avoid submitting to the dictates of donors within the limited window of maneuver that still remains (?) for Senegal.
1. Tailor-made , taking into account the specific characteristics of Senegal's public debt
First, the aim here will be to create a way out of the current impasse, by prioritizing a strategy of technical renegotiation of the macro-fiscal framework with the International Monetary Fund (IMF).
This approach will consist of two macro metrics, namely:
a) Reassure the IMF about the technical parameters within this framework ; growth path, GDP, elasticity of reforms, tax floatability, overhaul/update of the PRES tax policy (whose failure is officially recognized and documented)
b) Acting via Asset/ Liability Management (ALM )
i. On Asset Management to increase solvency through prudent and progressive monetization of strategic assets ( asset-recycling , overhaul of the administrative structure, work on the public sector, e.g. SENELEC, PETROSEN, LA POSTE, etc.)
ii. On Liability Management through financial innovations such as Debt Swaps (debt exchange mechanisms, such as Energy Debt in Zambia, etc.)
2. Benchmark on recent restructuring failures and successes
The idea here is to draw inspiration from what has worked or not worked in countries facing the same public finance situation as Senegal; this in order to draw lessons to adapt in the local context.
The approach must avoid a triple obstacle: (1) a divisive sequencing, by favouring particular creditors over others; (2) the use of financial innovations whose risk is not controlled such as Total Return Swaps (TRS) and finally (3) the brutal treatment of domestic debt.
The examples of Zambia, Ghana, and Ethiopia, whose restructurings are still underway, provide interesting benchmarking points for several reasons. For instance, regarding TRS (Total Return on Securities), the benchmark can be based on the case of Ukrainian Eurobonds in 2015, given the absence of a cap on the warrants linked to GDP, as reflected in the €20 billion contingent liabilities.
3. Optimized debt treatment
The current structure of the creditors of the State of Senegal is not simple. Analysis suggests a pragmatic approach that would allow for a dual objective: firstly, to initiate a dynamic of preventive and coordinated negotiation among external creditors; and secondly, to protect the balance sheets of regional actors, particularly through innovative mechanisms.
a) On external debt
The proven mechanism of the G20 Common Framework, which has already demonstrated its effectiveness, should be used, with a clear timetable for negotiations specifying the timeframe and any potential obstacles. This timetable must be based on the sharing of up-to-date information, and during this process, the coordinated and recognized publication by all stakeholders of the Debt Sustainability Analysis (DSA), a true diagnostic tool that allows for a thorough examination of the patient's condition and the identification of the underlying problems. This step is a prerequisite for any Staff Level Agreement (SLA) with the IMF and external lenders.
Ideally, the presentation of the External Debt Treatment Strategy ( EDTS ) should precede an IMF Executive Committee meeting, with a Global Investor Call to private creditors and a roadshow to major lenders (IMF, World Bank, MDB, bilateral creditors France, China, EU, etc.).
b) On domestic debt.
On this point, it will be necessary to distinguish the debt itself from that backed by the TRS; the latter must be treated in a specific way as it is a bridge between domestic and external debt by means of possible clauses triggering margin calls.
For non-TRS debt, Debt Swaps type mechanisms could be implemented, similar to what was done by Barbados in 2025.
Such a move towards clarity, transparency, and foresight could allow us to re-establish dialogue with the international financial community and move beyond the unfortunate episode of "hidden debt."
By Mr. Seydina Alioune NDIAYE, Economist
SENQUANT Partner






Commentaires (7)
Participer à la Discussion
Règles de la communauté
💡 Astuce : Utilisez des emojis depuis votre téléphone ou le module emoji ci-dessous. Cliquez sur GIF pour ajouter un GIF animé. Collez un lien X/Twitter, TikTok ou Instagram pour l'afficher automatiquement.
Se connecter
Commentez avec votre profil, votre photo, et soyez averti des réponses.